

Buying a home is one of the biggest financial decisions most people will make in their lifetime. Yet many young adults reach the point of wanting to buy their first property without a clear understanding of how the property market works, what it costs to own a home or even the difference between buying and renting.
While children might be a long way from signing a contract or saving for a deposit, there’s plenty parents can do to help them build a solid foundation early.
Teaching kids about property doesn’t mean turning family conversations into economics lessons or expecting them to understand interest rates before they’ve mastered their times tables. It’s about introducing everyday concepts, encouraging curiosity and helping them understand the relationship between money, housing and the choices people make.
Start early, keep it practical and make it enjoyable, and those small lessons could pay dividends when they’re ready to make property decisions of their own.
Start With The Home You Live In
One of the easiest ways to introduce children to property is to talk about the home they already know.
Explain that a house or apartment is more than just somewhere to sleep. It’s an asset that someone owns, a place that requires ongoing maintenance and a space that comes with costs such as electricity, water, insurance and council rates.
Depending on their age, you could explain that some families own their homes while others rent. Both provide somewhere to live, but the arrangements are different.
Homeowners generally have responsibility for maintaining their property and may build equity as they pay down a mortgage. Renters pay to live in a property owned by someone else, usually under a rental agreement that sets out their rights and responsibilities.
These simple distinctions help children understand that housing involves decisions, costs and obligations, not just choosing a place they like.
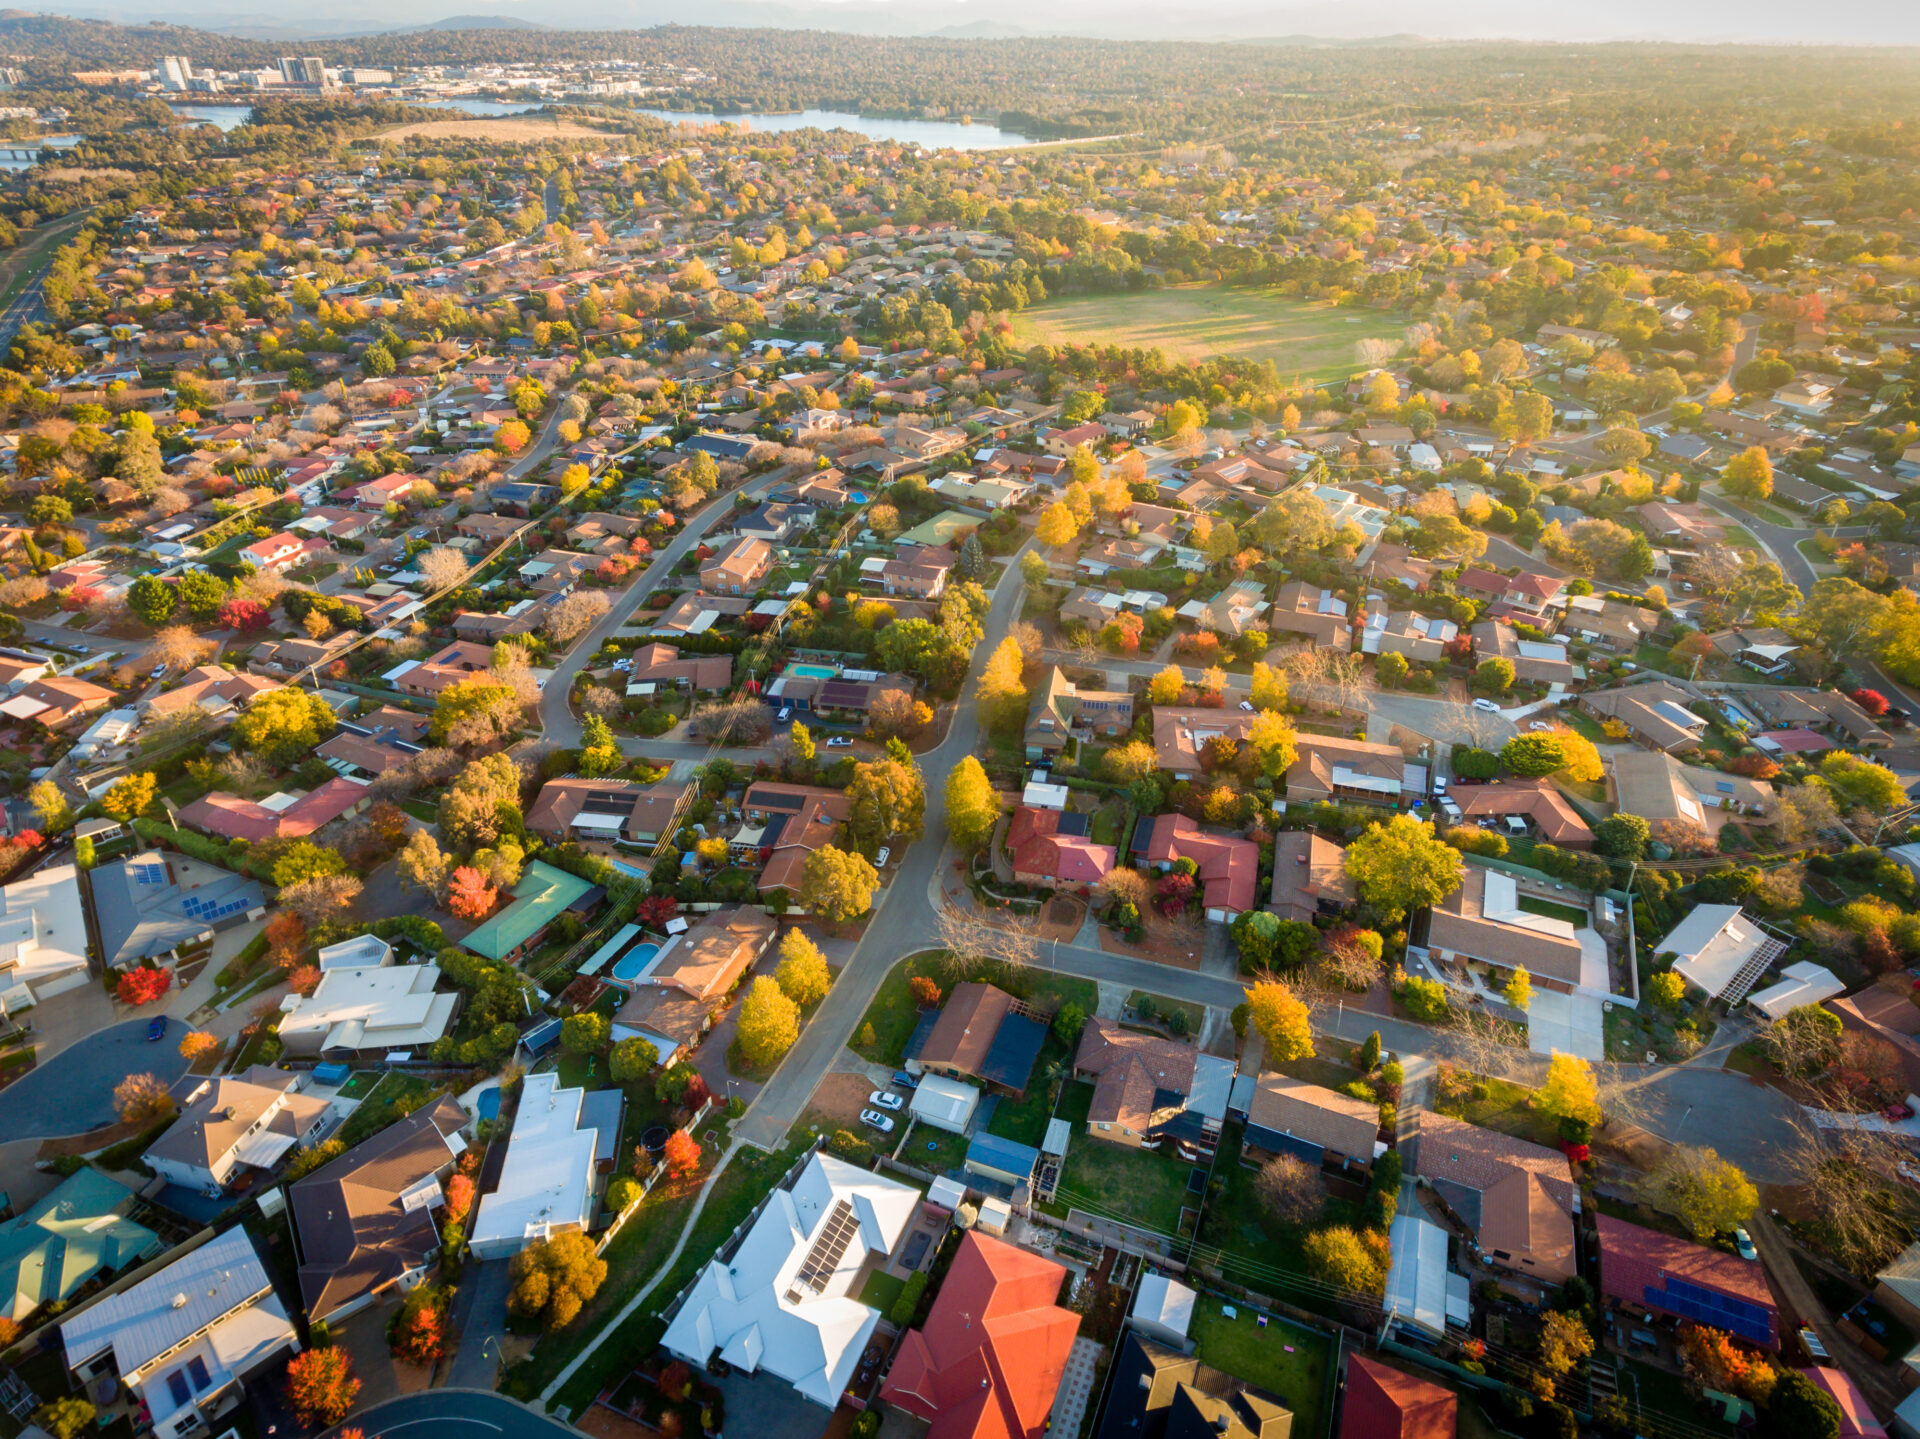
You can also introduce the idea that homes come in different forms. A freestanding house, townhouse, apartment and unit all provide accommodation, but they can differ in size, location, price, maintenance requirements and access to shared facilities.
Next time you walk through your neighbourhood, ask your children which types of homes they notice and why different families might choose to live in them.
Make Monopoly a Property Lesson
If there’s one family board game that can help introduce the basics of property, it’s Monopoly.
The game provides a simple way to explore buying, selling, renting and managing money, all while having a bit of fun. Children can see how purchasing a property involves an upfront cost, how owning several properties can generate rental income and how unexpected expenses can affect their available cash.
When a player lands on a property they don’t own, they may have the opportunity to buy it. If another player owns it, rent may be payable. Build enough properties and houses, and the potential income increases, but so does the amount of money tied up in the game.
Parents can use these moments to ask questions.
Would you spend most of your money buying this property, or keep some cash aside? Why might someone choose to own several smaller properties rather than one expensive one? What happens if you have valuable properties but not enough cash to cover a bill?
These questions introduce concepts such as budgeting, cash flow, risk and opportunity cost without needing complicated explanations.
Of course, Monopoly is a simplified version of the real world. Actual property transactions involve legal contracts, inspections, finance, taxes, ongoing expenses and market conditions. Rent isn’t guaranteed and property values don’t always rise. It’s worth pointing out these differences so children understand that the game is a starting point rather than a blueprint for investing.
Still, it’s a great way to turn abstract ideas into something they can see, discuss and experience.
Take Property Learning Beyond The Board Game
Once children begin to understand the basics, everyday activities can help bring the property market to life.
Explore the neighbourhood
Next time you’re out for a walk or driving through a new suburb, look at the different homes around you. Talk about the differences between houses, townhouses, apartments and units, and consider why someone might choose one over another.
You might discuss proximity to schools, public transport, shops, parks and workplaces, or how a smaller home close to amenities could suit someone better than a larger home further away.
This introduces the idea that property value isn’t determined by the building alone. Location, convenience, condition and the surrounding area can all influence what buyers are prepared to pay.
Browse property listings together
Online property listings can provide a useful window into how the market works.
Choose a few homes in different locations and compare their advertised prices, features, size and condition. Ask your children which property they think might cost more and why.
You could look at a house with a backyard, an apartment close to public transport and a townhouse near local shops. Discuss the trade-offs involved in each option.
Older children can also learn the difference between an asking price and the final selling price, and why a property’s advertised price doesn’t necessarily tell the whole story.
The aim isn’t to teach them to predict property prices. It’s to help them understand that homes differ, buyers have different priorities and market values are influenced by a range of factors.
Talk about renting as well as buying
It’s easy to focus on homeownership when discussing property, but renting is an important part of the picture.
Explain that renting allows people to live in a property without buying it, while providing the rental provider with income. In return, renters have obligations under their rental agreement, including paying rent and looking after the property.
You can also discuss the costs associated with renting, such as rent, a bond and moving expenses, alongside the costs of owning a home.
As children get older, introduce the idea that renting can suit people at different stages of life. Someone might rent while studying, starting a career or saving for a deposit. Others may choose to rent long term because it suits their circumstances.
Understanding both options helps young people appreciate that there isn’t one housing arrangement that works for everyone.
Introduce The Real Cost of Owning Property
A common misconception among young buyers is that the purchase price is the only major cost involved in buying a home.
Parents can help children develop a more realistic picture by explaining that ownership comes with ongoing expenses.
There may be mortgage repayments, council rates, insurance, repairs, maintenance and utility bills. Buyers may also face upfront costs such as conveyancing, inspections, loan fees and, where applicable, stamp duty.
Younger children don’t need to know the details of every expense. Simply explaining that owning a property requires money beyond the initial purchase is a useful starting point.
For teenagers, you could take this further by creating a basic monthly budget for an imaginary household. Include income, housing costs, food, transport, bills and savings. Ask them what they would do if the hot water system needed replacing or their income changed.
It’s a practical way to demonstrate why financial preparation matters and why spending every available dollar on a purchase can leave a household vulnerable to unexpected costs.
Help Them Understand Saving and Patience
Property can also be an opportunity to teach children about setting goals and saving consistently.
You don’t need to suggest that every child must buy a home. Instead, explain how saving can create options and help people prepare for larger purchases.
Younger children could save pocket money towards a toy or bicycle, while teenagers might work towards a car, travel or future study expenses. The underlying lesson is the same: goals often require planning, patience and making choices about how money is spent.
As they get older, you can explain how adults may save for a home deposit, why lenders assess a borrower’s ability to repay a loan and how interest affects the total cost of borrowing.
It’s also worth explaining that a deposit is only one part of preparing to buy. Buyers need to consider their income, expenses, borrowing capacity, upfront costs and ability to manage repayments over time.
These lessons build financial confidence without placing unnecessary pressure on young people to achieve homeownership by a particular age.
Let Teenagers Follow The Market
For older children, following local property news can be a useful way to connect these early lessons with the real world.
You could look at how interest rate changes affect borrowing costs, why some suburbs attract more buyer interest than others or how new transport links and local infrastructure may influence an area.
Discuss why a property that suits one buyer might not suit another and why market conditions can change. A home that attracts strong competition in one period may receive a different response when borrowing costs rise or buyer confidence changes.
It’s also a good opportunity to explain that property markets are local. National headlines might describe broad trends, but prices and demand can vary significantly between suburbs, property types and individual homes.
Encourage teenagers to ask questions, compare information and distinguish between facts, opinions and predictions. They don’t need to become property experts. Developing the habit of thinking critically about the market is what matters.
Teach Them to Ask The Right Questions
As children get older, the focus can shift from understanding property basics to knowing what to investigate before making a decision.
If they eventually want to rent, buy a home or invest in property, they’ll need to consider more than whether they like the look of a place.
Useful questions include:
- What can I realistically afford?
- What ongoing costs will I need to cover?
- Does the location suit my needs and lifestyle?
- What condition is the property in?
- What legal documents and obligations should I understand before signing?
- What could happen if my income or circumstances change?
- Where can I get reliable, independent advice?
Knowing when to ask for professional help is just as important as understanding the basics. Conveyancers, building inspectors, mortgage brokers and qualified property professionals each have different roles in a transaction.
Helping young people recognise those roles can make the process less intimidating when they eventually enter the market themselves.
Build Confidence, Not Pressure
It’s important to remember that learning about property should be empowering rather than overwhelming.
Not every young person will want to buy a home, and circumstances such as income, employment, location and personal priorities will influence their options. The aim isn’t to convince children that property ownership is the only path to financial security.
Instead, it’s to give them the knowledge to understand their choices, weigh up the costs and responsibilities and make informed decisions when the time comes.
Some children will learn through games such as Monopoly. Others will respond to neighbourhood walks, comparing listings or helping plan a household budget. The best approach is one that fits their age and interests.
Small Lessons Today Can Make a Difference Tomorrow
Property can seem complicated when you first encounter it as an adult. There are prices to compare, finance to arrange, contracts to understand and long-term responsibilities to consider.
But many of these concepts become easier to grasp when they’ve been introduced gradually over time.
By talking openly about housing, playing Monopoly, exploring property listings and encouraging good money habits, parents can help their children develop a practical understanding of the market well before they need to make a transaction of their own.
They might not remember every conversation or game, but the lessons can stay with them. Ask questions, understand the costs, plan ahead and never rush into a major decision without doing your homework.
And when the time comes to take their first steps into the property market, that early knowledge could prove invaluable.
Need more advice? Contact an Elders Expert in your area here.