

The big story heading into 2027 is that Australia’s property market is facing a very different set of conditions after five interest rate increases in 2026. Higher mortgage costs, persistent inflation and softer buyer demand have taken some heat out of housing prices. But does that mean another difficult year ahead, or could 2027 bring the beginnings of a recovery?
The Reserve Bank of Australia’s latest forecasts suggest inflation will take longer to settle than previously hoped, meaning borrowers and buyers may need to remain patient.
Looking Back: Five Rate Hikes in 2026
After three interest rate cuts in 2025, the RBA began reversing course in February 2026 as inflation picked up and demand across the economy proved stronger than expected.
The cash rate increased by 0.25 percentage points in February, March and May, taking it from 3.60% to 4.35%. The RBA then held rates steady at its June and August meetings, giving households and businesses some breathing space while it assessed the impact of those increases.
However, inflation remained stubborn, with higher fuel and commodity prices adding to existing cost pressures. The RBA raised rates again in September and November, taking the cash rate to 4.85%, a total increase of 1.25 percentage points across the year.
For homeowners with a mortgage, the impact has been significant. Higher repayments have placed additional pressure on household budgets, leaving less room for discretionary spending, renovations and other major purchases. Businesses have also faced higher borrowing and operating costs, while prospective buyers have had to reassess how much they can comfortably afford to borrow.
What Has This Meant For The Property Market?
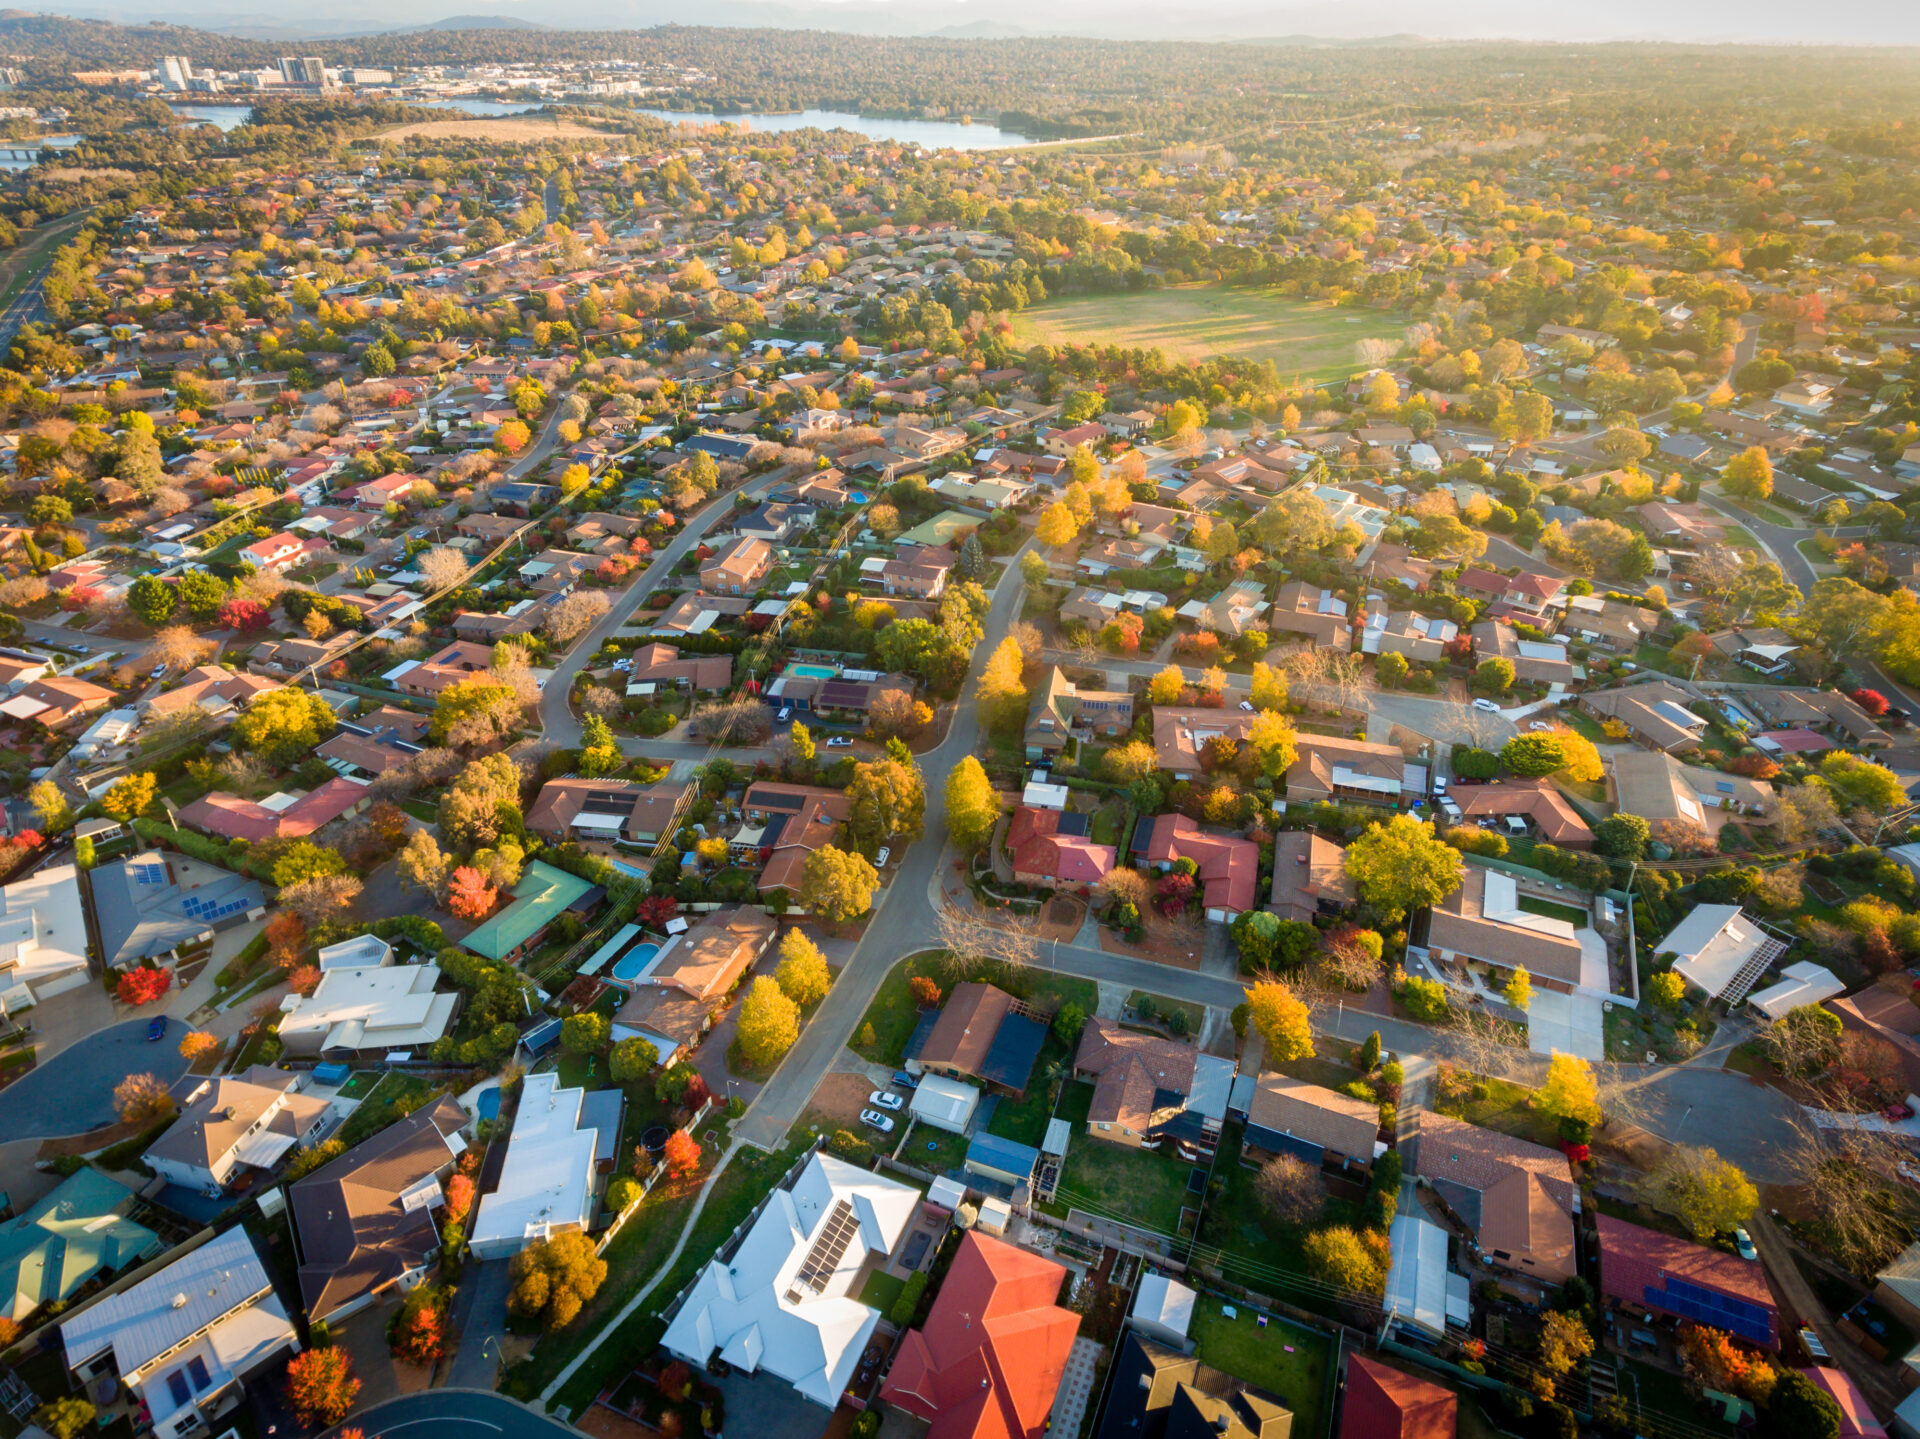
Higher interest rates have gradually reduced borrowing capacity and buyer confidence, contributing to a noticeable change in housing market conditions.
According to the RBA’s November Statement on Monetary Policy, national housing prices were 4.7% below their March 2026 peak by September. Auction clearance rates remained low, properties were taking longer to sell and overall transaction activity had softened.
The downturn has also spread beyond Sydney and Melbourne, with price declines becoming more widespread across the capital cities. Investor activity has weakened particularly sharply, with new housing loan commitments falling as borrowing costs and changes to property tax settings have affected purchasing decisions.
For sellers, this has meant adjusting expectations, paying closer attention to presentation and pricing, and allowing more time to find the right buyer. Buyers, meanwhile, may have more opportunity to negotiate and take their time researching properties rather than competing in the fast-moving conditions experienced during previous growth periods.
Importantly, not every location or property type is experiencing the same conditions. Local employment, housing supply, affordability, population growth and buyer demand continue to influence individual markets.
What Could The 2027 Property Market Look Like?
Interest rates will remain a key influence. Financial markets were pricing in around one and a half additional rate increases by mid-2027 ahead of the RBA’s November decision. While this is not a guarantee of further increases, it highlights the uncertainty borrowers and buyers may face.
There are also factors that could help support the market. Australia’s ongoing housing supply challenges, population growth and demand for rental accommodation remain important considerations. If interest rates eventually stabilise and inflation begins easing, buyer confidence could gradually improve.
For buyers, a softer market may create opportunities to negotiate, particularly where sellers are motivated. For homeowners considering selling, understanding local comparable sales and setting realistic expectations will be important. Investors will need to assess rental demand, holding costs and potential returns carefully.
What Does The RBA Expect Inflation To Do in 2027?
Inflation remains the biggest obstacle to a more favourable interest rate outlook.
In its November 2026 forecasts, the RBA expects headline inflation to peak at 4.5% in the December quarter of 2026 before easing. However, both headline and underlying inflation are now expected to remain above 3% until late 2027.
The Bank forecasts headline inflation of 2.7% and underlying inflation of 2.9% by December 2027, moving towards the midpoint of its 2–3% target range around mid-2028.
Higher global energy prices, ongoing conflict-related costs, domestic capacity pressures and persistent business expenses are contributing to the slower return to target. The RBA also expects economic growth to remain below its potential rate, with unemployment forecast to reach 4.9% by December 2027.
A Year For Patience and Perspective
After five rate increases, Australian households and property markets are feeling the effects of tighter monetary policy. While 2027 may bring further price adjustments, it could also provide opportunities for buyers and a period of greater stability as inflation gradually eases.
The key will be looking beyond national headlines. Property markets are shaped by local conditions, and individual suburbs can perform quite differently even when the broader market is slowing.
For homeowners, buyers and investors, understanding those local differences and making decisions based on their own circumstances will be particularly important as Australia moves into 2027.